A review of waning U.S. recovered paper trades and output
The near- to medium-term recovered paper trade and production outlook appears subdued
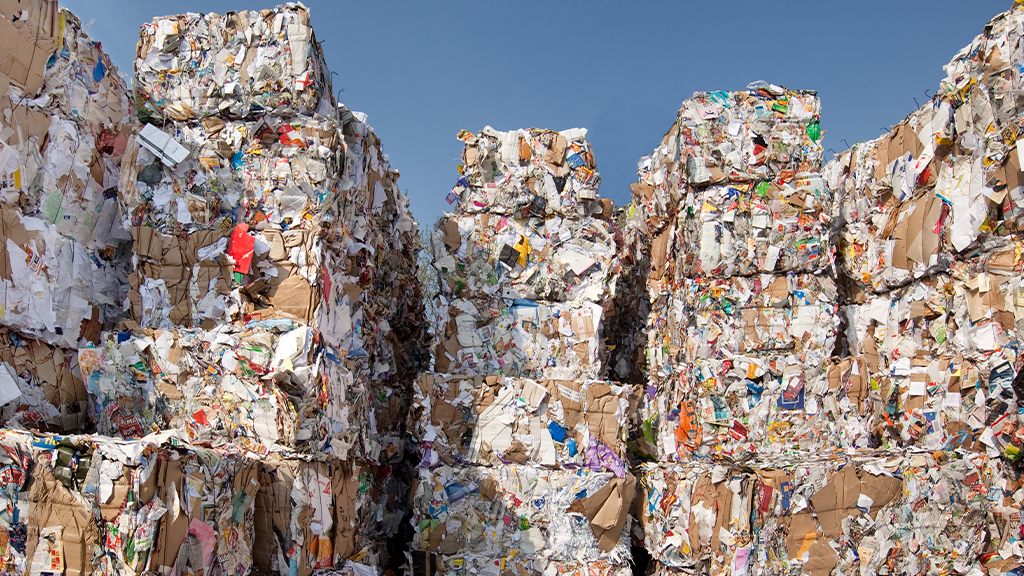
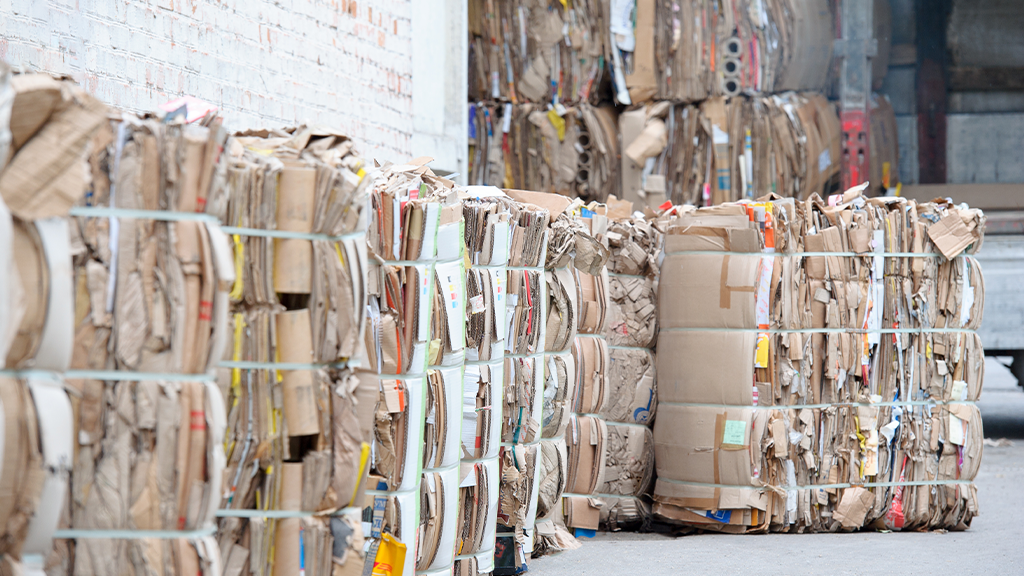
U.S. recovered paper exports declined 1.2 percent between January and May 2026, while imports fell 16.7 percent annually, according to Census Bureau data. Does this trend signal strong reshoring or waning trade?
During the first five months, total shipped recovered paper volumes were 5.58 million net tons (5.07 million tonnes) compared to 5.65 million net tons in the year-ago period. Import volumes in this time frame were approximately 276,000 net tons, against 332,000 net tons.
Recycled fibre shipments from and into the U.S. have been flat to low since January this year. However, export volumes have held steady at about five million net tons since 2024, while import volumes have nearly halved from almost 400,000 net tons two years earlier.
Stable export demand
On a positive note, Asian demand for export-grade recovered paper has been unwavering. India, Malaysia, Thailand, and Vietnam have remained among the top five buyers in 2026 and 2025.
India and Thailand hold a majority share of total exports, with volumes between 850,000 and 900,000 net tons on average since 2024. Malaysia and Vietnam have constantly purchased 600,000-800,000 net tons, although Malaysia has bought approximately 6-12 percent lower volumes over two years.
Outside of Asia, Mexico has been a constant importer, although shipments since 2024 have declined about 14 percent, to approximately 650,000 net tons, from 722,000 net tons.
Lower imports
The U.S. has been a strong exporter of recovered paper; however, it has consistently reduced dependence on imports over time. Recent government legislation on tariff changes and disruptions to deep-sea routes have been the main drivers of falling volumes.
Since 2024, shipments into the country have dropped about 35-40 percent to 276,000 net tons from 444,000 net tons. Canada and Mexico remain the top sellers; however, shipments from Mexico have decreased 50 percent on average to 6,600 net tons, down from 28,000 net tons over two years. Similarly, volumes from Canada are 15-20 percent lower, at 269,000 net tons, from 413,000 net tons.
Rangebound prices in 2026 after weakening in 2025
In terms of export prices, the weekly Davis Index data shows the average price of #11 Old Corrugated Containers (OCC) has gradually moved up to $35 per net ton, free alongside ship (FAS) between January and May 2026. The grade reached $145 per net ton FAS in New York and Los Angeles during May, a level last seen in January 2025.
Prices had trended flat for most of 2026, moving up barely five dollars per net ton every week until mid-March. Market participants indicated that the uptick began after mid-April, with the steepest incline of $20 per net ton seen around April 20 until mid-May.
Export prices out of New York and Los Angeles reached an annual low of $105-106 per net ton in November 2025, with a gradual recovery after late December.
Low domestic production
According to several market participants, the U.S. domestic containerboard market has been bearish this year, which has in turn affected export volumes and pricing.
Data from the American Forestry and Paper Association (AF&PA) indicates that annual containerboard production has fallen three to five percent in the first half of 2025 and 2026 after climbing seven percent in the first six months of 2024.
Moreover, total output slipped two percent annually in Q2 2026, while domestic demand improved one percent annually during the review quarter.
Circular economy ESG leader and executive advisor Myles Cohen reiterated to Davis Index that domestic containerboard volumes have dropped. Structural changes such as mill closures, lightweighting, and revised packaging norms have had a much deeper impact on containerboard production. The industry has declined steadily over the last decade, compared with an annual one to three percent growth 20 years ago.
According to Cohen, although 30 percent of the lost output can be regained if the economy improves, a majority (nearly 60 percent) goes into landfills, incinerators, or is disposed of.
Several market participants have also hinted that local generation volumes have remained low, creating a supply-demand imbalance, with annual volumes steadily dropping. Cohen stressed that there is significant untapped potential to improve paper recycling rates from avenues besides residential collection.
The near- to medium-term recovered paper trade and production outlook appears to be subdued. Although export prices have increased recently, market participants anticipate recycled fibre export and import activity will remain moderate through the remainder of 2026. If that forecast holds, recycled fibre prices (domestic and export) will likely remain soft to sideways until December this year.
______________________________________________________________________________________
Huban Kasimi is the Recycled Materials Editor at Davis Index and can be reached at [email protected].
This article originally appeared in the September/October 2026 issue of Recycling Product News.